A homebuyer can hear two reassuring sentences in the same week: “Your home loan sanction has come through” and “This is a bank approved project.” Both sound like approval. Both involve a lender.
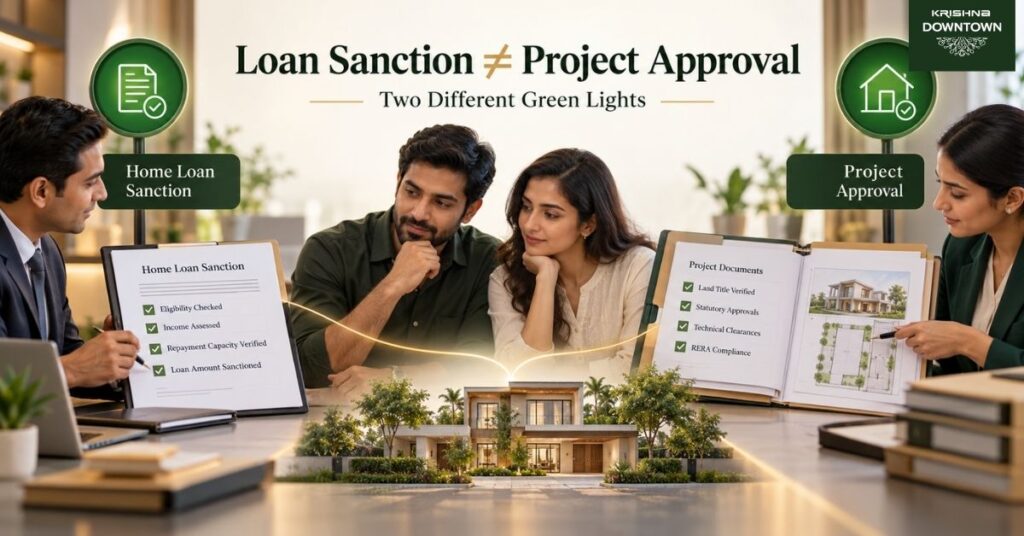
A homebuyer can hear two reassuring sentences in the same week: “Your home loan sanction has come through” and “This is a bank approved project.” Both sound like approval. Both involve a lender. But they do not mean the same thing — and confusing them can create problems just when you are preparing to pay a booking amount, sign an agreement or schedule registration.
For anyone evaluating a villa in Bhubaneswar or villa in Phulnakhara, the simplest way to understand the process is to imagine two separate green lights. The first green light is for you as a borrower. The second is for the property or project. A smooth purchase usually requires both, plus completion of the lender’s documentation and disbursement conditions.
Quick Answer A home loan sanction means the lender has assessed your financial profile and is willing to lend a stated amount subject to terms and conditions. Project approval means the lender has separately reviewed a housing project/property for funding under its legal and technical norms. A sanctioned borrower can still face delay or refusal at property evaluation, and a bank approved project does not mean every buyer will qualify for a loan. |
Imagine you have a sanction for ₹60 lakh. You then shortlist a villa and assume the bank will automatically release ₹60 lakh because “the project is approved.” That conclusion may be premature. The sanctioned amount can be subject to conditions, property value, legal/technical verification, margin requirements and the lender’s rules. The final disbursed amount can also depend on the selected property and the stage of construction.
Now reverse the situation. A developer says the project is approved by several leading banks. That is useful because it indicates those lenders have completed some project-level due diligence for their own funding process. But it does not mean your home loan eligibility has been established. The bank will still examine your income, age, existing obligations, credit profile, repayment capacity, KYC and other borrower-specific factors.
The practical rule is straightforward: project approval reduces one layer of uncertainty; borrower sanction reduces another. Neither is a substitute for the other.
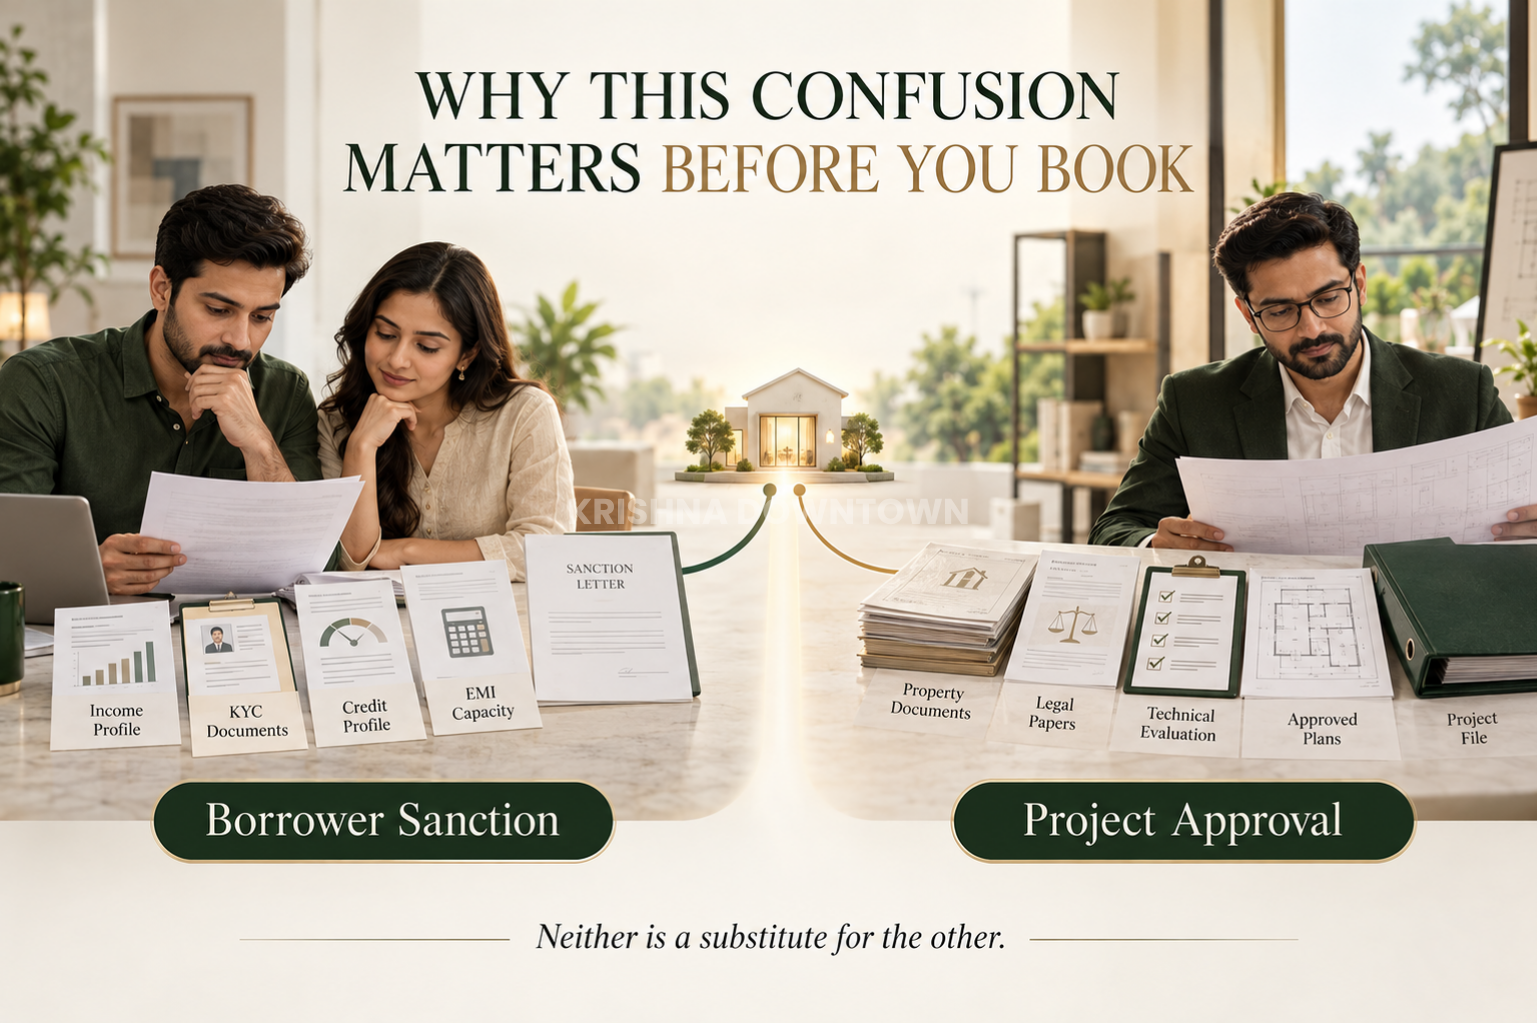
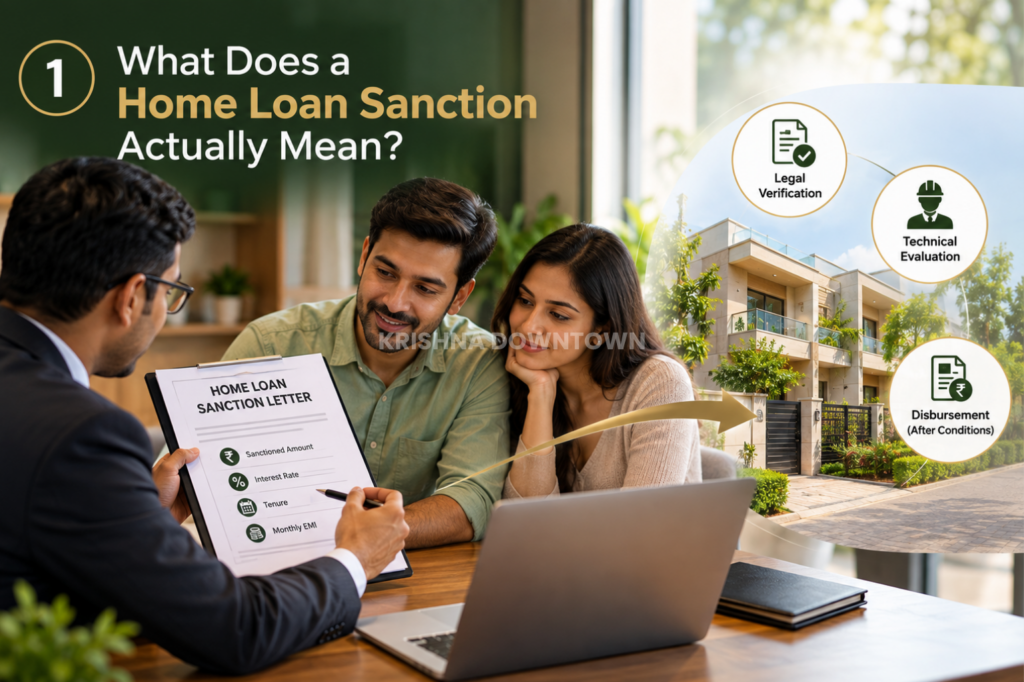
A home loan sanction letter is the lender’s formal communication that your application has been assessed and approved for a specified amount under stated terms, subject to conditions. Banks typically evaluate information such as income, employment or business profile, credit history, age, existing EMIs and repayment capacity before issuing sanction.
The sanction letter can include the sanctioned amount, interest-rate structure, tenure, estimated EMI, charges, validity period and conditions that must be met before home loan disbursement. This is why a sanction should be read carefully rather than treated as a simple “yes.”
A crucial point: sanction can sometimes happen before the final property is identified. That proves why sanction is primarily about the borrower’s capacity and eligibility. Once a property is selected, the lender may still need to carry out property legal verification and property technical evaluation before releasing funds.
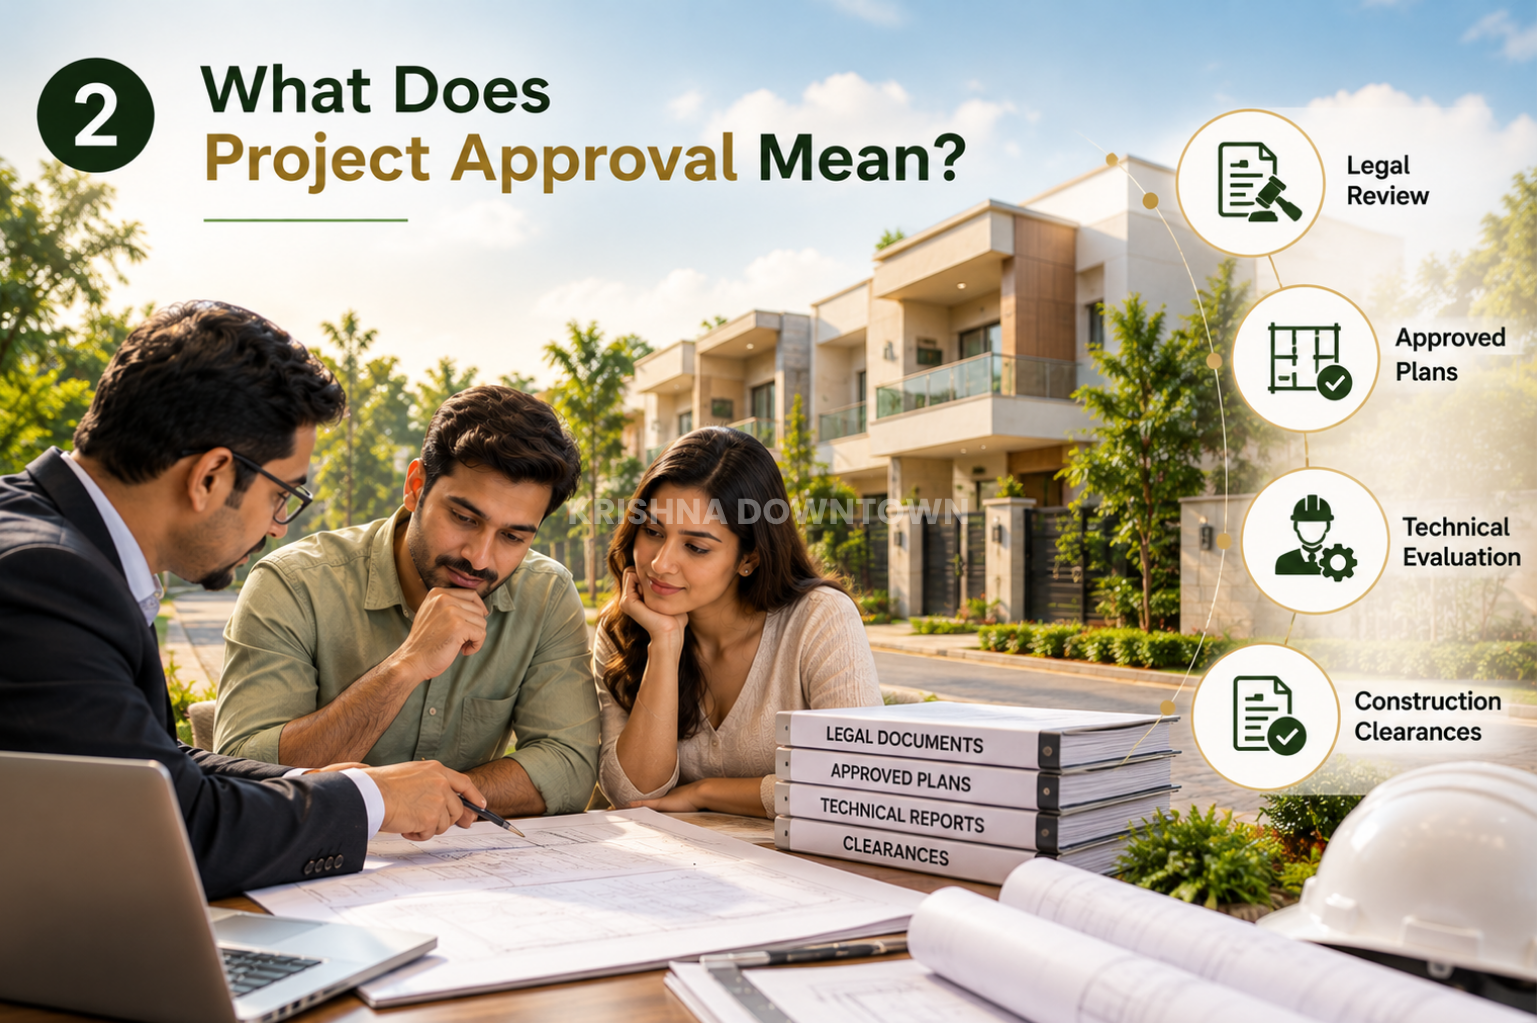
For home-loan purposes, project approval generally means a lender has reviewed a developer/project and its documents to determine whether homes in that project can be considered for funding under the lender’s internal norms. The review may include title and legal documents, sanctioned/approved plans, construction-related clearances and technical aspects relevant to the lender.
Some lenders use terms such as approved project, builder tie-up or Approved Project Finance/APF. The terminology and scope can vary. What matters to the buyer is the current status of the exact project — and where relevant, the exact phase or unit — with the bank from which the buyer intends to borrow.
One bank’s project approval is not automatically another bank’s approval. Lenders can use different legal, technical, credit and risk criteria. That is why the buyer should verify approval directly with the chosen lender, not only rely on a sales brochure, WhatsApp message or verbal statement.
Question | Home Loan Sanction | Project Approval |
What is being evaluated? | The borrower | The property/project |
Main purpose | Assess home loan eligibility and lending terms | Decide whether the lender is comfortable funding homes in that project |
Typical checks | Income, employment/business, credit profile, age, existing liabilities, repayment capacity | Title/legal papers, approvals/plans, technical viability, project documents and lender-specific criteria |
Key output | Home loan sanction letter / approval subject to conditions | Project appears in lender’s approved/tie-up/project-finance process or receives lender-specific approval |
Guarantees disbursement? | No. Property checks and conditions may still remain. | No. Borrower must still qualify and fulfil loan conditions. |
Same across all banks? | No. Eligibility and terms vary by lender. | No. A project approved by one lender may not be approved by another. |
Buyer action | Read amount, tenure, rate, fees, validity and conditions carefully | Confirm current approval directly with the chosen lender for the relevant project/phase/unit |
This distinction becomes clearer when you separate the lender’s two risks. The first is borrower risk: can this applicant repay the loan? The second is property risk: is this property acceptable security and fundable under the lender’s rules?
A financially strong borrower can select a property that does not satisfy a lender’s legal or technical criteria. Likewise, a lender may be comfortable with a bank approved project, but an individual applicant may still qualify for a lower amount than expected or may not meet the lender’s credit policy.
That is also why home loan disbursement is a separate milestone from sanction. Official lender guidance commonly places property evaluation and document completion between sanction and disbursement. So buyers should plan cash flows and booking commitments around the full process — not just the date of the sanction letter.
Buyer Rule Do not schedule a non-refundable payment merely because one stage is complete. Ask the lender: “What exactly is still pending before disbursement for this specific property?” |
Assumption | What the buyer should know |
“My loan is sanctioned, so the bank has cleared the property.” | Not necessarily. A home loan sanction can precede final property evaluation. Ask whether legal and technical clearance for the selected unit is complete. |
“The project is bank approved, so my loan is guaranteed.” | No. Home loan eligibility remains borrower-specific. |
“If Bank A approved the project, Bank B must approve it too.” | No. Lenders can reach different decisions. ICICI Bank’s own guidance explicitly says one bank’s approval does not necessarily mean another will approve the same project. |
“Bank approval is the same as RERA registration.” | No. RERA registration is a regulatory requirement/status under real-estate law where applicable; lender project approval is a bank’s financing decision. |
“RERA registration means I can skip document verification.” | No. ORERA gives buyers an official place to check registered project information, but a buyer should still review documents and the exact transaction with appropriate professional advice. |
“Sanctioned amount equals final disbursement.” | Not always. Property value, LTV/margin, legal/technical outcome and conditions can affect the amount and timing of home loan disbursement. |
“A sales executive’s bank list is enough proof.” | Treat it as a starting point. Confirm current project/phase approval directly with the lender you intend to use. |
A RERA registered project and a lender-approved project answer different questions. The Real Estate (Regulation and Development) Act requires registration of applicable projects before they are advertised, marketed, booked or sold, subject to statutory exemptions. Odisha buyers can use the Odisha Real Estate Regulatory Authority (ORERA) portal to search registered projects and review available project information.
But RERA registration should not be treated as your personal loan approval, and a lender’s project approval should not be treated as RERA registration. A careful buyer uses both systems for what they are designed to do: regulatory transparency on one side, financing due diligence on the other.
Suppose a family searching for a home loan for villa in Bhubaneswar first gets a sanction based on salary, existing liabilities and credit profile. They then shortlist a villa in Phulnakhara. At this point, they should not assume that their financial sanction automatically clears the villa. They should ask their lender whether the project is currently approved for home-loan funding and whether any unit-specific legal, technical or valuation checks remain.
The reverse is equally important in Phulnakhara real estate. A project may have relationships or approvals with multiple lenders, yet the buyer still needs to qualify individually. Someone with a strong down payment but high existing EMIs may receive a different sanction than a buyer with the same income but fewer liabilities. The project did not change; the borrower profile did.
This is why a finance-ready site visit should include more than asking, “Which banks are tied up?” Ask for the project’s current lender list, then independently contact the bank you are likely to use. That small step can prevent last-minute surprises between booking and registration.
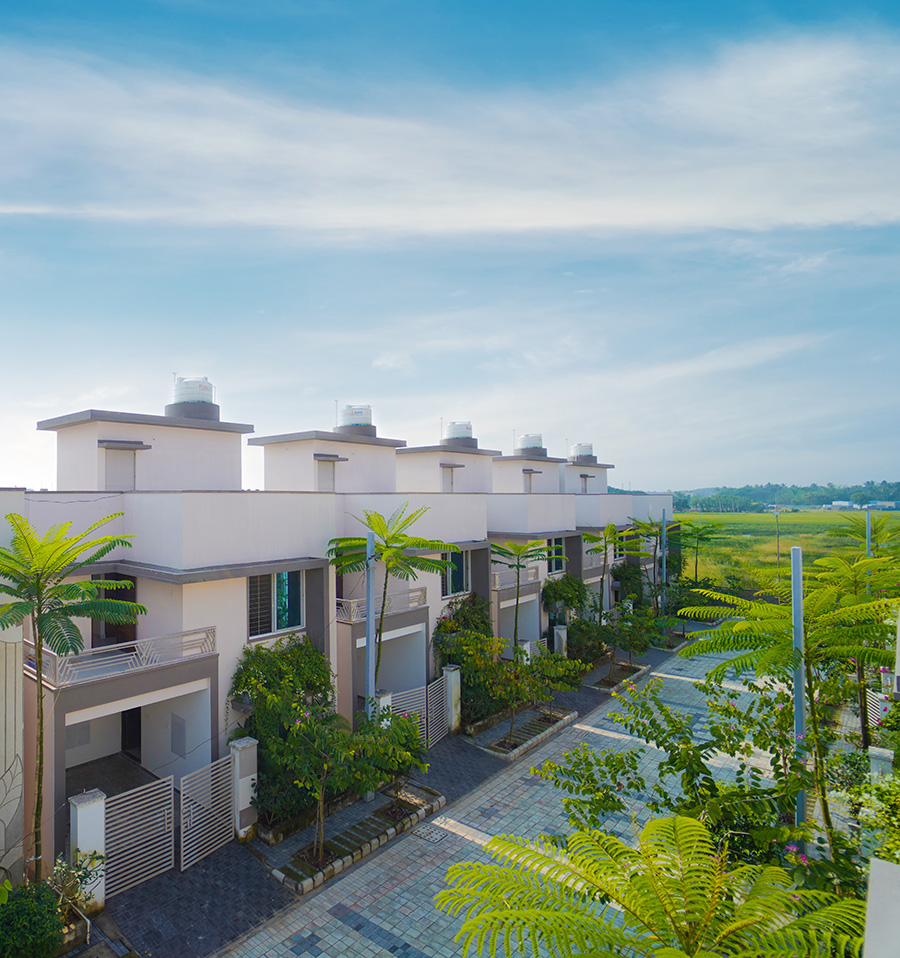
For families evaluating Krishna Downtown in Phulnakhara, the official project website currently presents the community as offering 3 BHK and 4 BHK villas, states that the project is RERA-approved, and lists approvals by leading banks including SBI, HDFC, ICICI, Axis Bank, Canara Bank and UCO Bank. Those statements are useful starting points for a financing conversation.
A buyer should still follow the same independent verification discipline described above: check the relevant project registration information on ORERA, ask the Krishna Downtown team which lender approvals are current for the phase/unit under consideration, and confirm that status directly with the chosen bank. Bank panels and lending policies can change, and individual home loan eligibility remains separate from project-level approval.
This is also the right way for Krishna Properties and Developer to build trust: not by presenting bank approval as a guarantee, but by helping buyers understand the documentation path, connect with lenders and verify what applies to their specific purchase.
Project Visit Tip When you visit Krishna Downtown, carry two checklists: one for the villa/site and one for finance. Ask the sales team for the current RERA/project documentation and lender-support details, then independently confirm the financing path with the bank before making a major non-refundable commitment. |
In real estate finance, the word “approved” is incomplete unless you ask: approved by whom, for what, for which project or unit, and subject to what conditions?
Your home loan sanction letter is not a legal certificate for the project. A bank approved project is not a promise that you personally will get the loan. RERA registration is not a bank sanction. And none of these replaces reading the agreement, checking current documents and understanding what remains before disbursement.
The good news is that once you separate these layers, the process becomes easier to manage. You know which questions belong to the lender, which belong to the developer, which belong to ORERA, and which require your own legal/financial review.
The simplest takeaway from home loan sanction vs project approval is this: sanction checks the buyer; project approval checks the property. Both matter, and neither should be stretched beyond what it actually confirms.
If you are comparing a villa in Bhubaneswar or villa in Phulnakhara, get clarity on your home loan eligibility early, but do not stop there. Verify the project with your chosen lender, check regulatory information, understand the sanction conditions and ask what remains before home loan disbursement. A few precise questions before booking can save weeks of confusion later.
Soft CTA Exploring villa living near Bhubaneswar? Schedule a site visit to Krishna Downtown, Phulnakhara, and ask the project team for the current documentation and lender-support details. Then confirm the applicable project approval and your own loan terms directly with your chosen bank before making a final financing decision. |
A home loan sanction is primarily an approval of the borrower’s loan application based on financial eligibility and lender conditions. Project approval is the lender’s separate review of the property/project for home-loan funding under its legal and technical criteria.
Yes. A sanction can be subject to property-level legal, technical, valuation and documentation checks. Home loan disbursement generally occurs only after applicable conditions and property requirements are satisfied.
No. A bank approved project means the lender is comfortable considering the project for funding under its norms. Your individual home loan eligibility is still assessed separately.
No. Lenders have different internal legal, technical and credit policies. Verify the exact project/phase with the bank you intend to use.
No. RERA registration is a regulatory status under real-estate law for applicable projects. Bank project approval is a lender-specific financing decision. Buyers should verify both independently.
Some lenders offer in-principle or pre-approved/sanctioned home-loan facilities before the final property is identified. Property documents and evaluation are then completed before disbursement, subject to lender terms.
Ask whether your sanction is final or conditional, whether the exact property/project has current lender approval, what legal/technical checks remain, what documents are pending, how much margin you must contribute and what must happen before home loan disbursement.
The official Krishna Downtown website currently lists approvals by leading banks. Buyers should ask the project team for current lender information and confirm the relevant project/phase status directly with their chosen bank, while separately checking their own loan eligibility and ORERA information.
Book a Personalized site visit to explore premium villas in Phulnakhara near Bhubaneswar
No Spam, We will only reach out for visit scheduling